
Question 1
Following the impairment review of the investment in BC, whatwould bethe carrying value ofthis associate in KL'sconsolidated statement of financial position at 31 December 20X9?
Correct Answer:
A. $1,050,000
Following the impairment review of the investment in BC, whatwould bethe carrying value ofthis associate in KL'sconsolidated statement of financial position at 31 December 20X9?
Which TWO of the following would be the primary disadvantages of producing the disclosures required in IFRS12 Disclosure of Interests in Other Entities?
The dividend yield of ST hasfallen in theyear to 31 May 20X5, compared to the previous year.
The share price on 31 May 20X4 was $4.50 and on 31 May 20X5 was $4.00. There were no issues of share capital during the year.
Whichof the following should explain the reduction in the dividend yield for the year to 31 May 20X5 compared to the previous year?
RS has issued an instrument with a nominal value of $1 million, at a discount of 2.5%, and a coupon rate of 6%. The terms of the issue are that the instrument must eitherbe redeemed at par, at the option of the holder, in three years' time, or alternativelyconverted into equity shares in RS.
The characteristics of this instrument taken as a whole indicates that it would be classified as which of the following?
When consolidating for group accounts, a number of calculations and adjustments are required to properly combine the entities into a single group. Which of the following processes are involved in this consolidation method?
Select ALL that apply:
BC are currently seeking to establish an accounting policy for a particular type of transaction.
There are four alternative ways in which this transaction can be treated. Each treatment will have a different outcome on the financial statements as follows:
* Treatment one means that the financial statements will be easier to prepare.
* Treatment two will give a fair representation of the transaction in the financial statements.
* Treatment three will maximise the profit figure presented in the financial statements.
* Treatment four means that the financial statements will be more easily understood by shareholders.
Which accounting treatment should BC adopt?
Ratios calculated from thefinancial statements of ST Group for the years ended 31 August 20X7 and 20X6 are as follows:
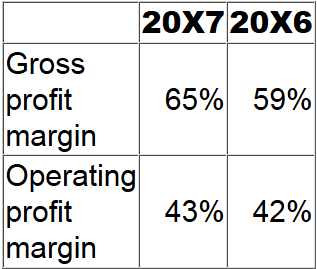
Which of the followingwould have contributed to the movements in these ratios?
Which TWO of the following are true in relation to IAS21 The Effects of Changes in Foreign Exchange Rates when consolidating an overseas subsidiary?
On 1 January 20X7 GH purchased plant and equipment at a cost of $400,000. The temporary differences in respect of this plant and equipment at 31 December 20X7 and 20X8 have been calculated as follows:
Assume that there are no other temporary differences in the periods and that the corporate income tax rate is 25%. GH is expected to have significant taxable profits in the future.
Which of the following is the correct impact in GH's statement of financial position at 31 December 20X8 in respect of deferred tax?
Which THREE of the following statements about preference shares are true?
Which of the following statements are INCORRECT with regards to impairment of financial instruments; Select ALL that apply.
Which of the followingreduce the usefulnessof ratio analysis when comparing entities that operate in the same industry? Select ALL that apply.
LM acquired 80% of the equity shares of ST when ST's retained earnings were $50 million. The fair value of the net assets of ST included a contingent liability with a fair value of $100 million at the date of acquisition and a fair value of $40 million at 31 December 20X6. No other fair value adjustments were required at the date of acquisition.
LM and ST had retained earnings of $200 million and $80 million respectively at 31 December 20X6.
The consolidated retained earnings of LM at 31 December 20X6 were:
On 1 January 20X7 GH purchased plant and equipment at a cost of $400,000. The temporary differences in respect of this plant and equipment at 31 December 20X7 and 20X8 have been calculated as follows:
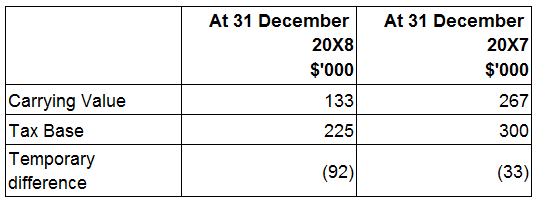
Assume that there are no other temporary differences in the periods and that the corporate income tax rate is 25%. GH is expected to have significant taxable profits in the future.
Which of the following is the correct impact in GH's statement of financial position at 31 December 20X8 in respect of deferred tax?
Following a wedding in October 20X0 ten people contracted food poisoning from eating food cooked by the wedding caterer PQ. At 31 December 20X0 PQ was advised by its legal advisors that aliability was possible but not probable and the incident was disclosed as a contingent liability at that date.
As the result of developments in the case, which is still not settled, PQ was advised that it is now probable, as at 31 December 20X1, that they will be found liable and will therefore have to pay damages of unknown value.
Which of the following would indicate that in the financial statements of PQ for the year ended 31 December 20X1 this should still be recognised as a contingent liability rather than a provision?